Commentary
President Trump has begun sending $500 checks to nearly one million people and enclosed a letter defending his record on cutting healthcare costs. The timing is awkward because it is only a month before voters go to the polls for the midterm elections. This makes the payment seem like a political payout.
In reality, the checks reflect a solid instinct concerning the future of American medical services. Trump and the Republicans declined to renew the government subsidies that have long kept the high prices of the wrongly named “Affordable Care Act” under control. This of course is Obamacare, the main pillars of which are still in place, wrecking American’s access to affordable and quality healthcare.
The Republicans were correct to pull the subsidies. Let the prices rise so that we can know the truth of what the ACA did to prices. There is no reason for taxpayers to continue to be on the hook to pay monolithic insurance companies and their myriad layers of bureaucracy. In Trump’s view, it makes much more sense to give the money to Americans directly to allow them to use it as they see fit.
This is an outstanding instinct. He is correct in every way. But there is a major problem. Nothing has been done to reform the system in a way that gives people more options on how to spend their health-care dollars. To save the money in a Health Savings Account requires that you have insurance. To leave the employer’s system—permitted under rarified circumstances—requires you to enroll in Obamacare exchanges.
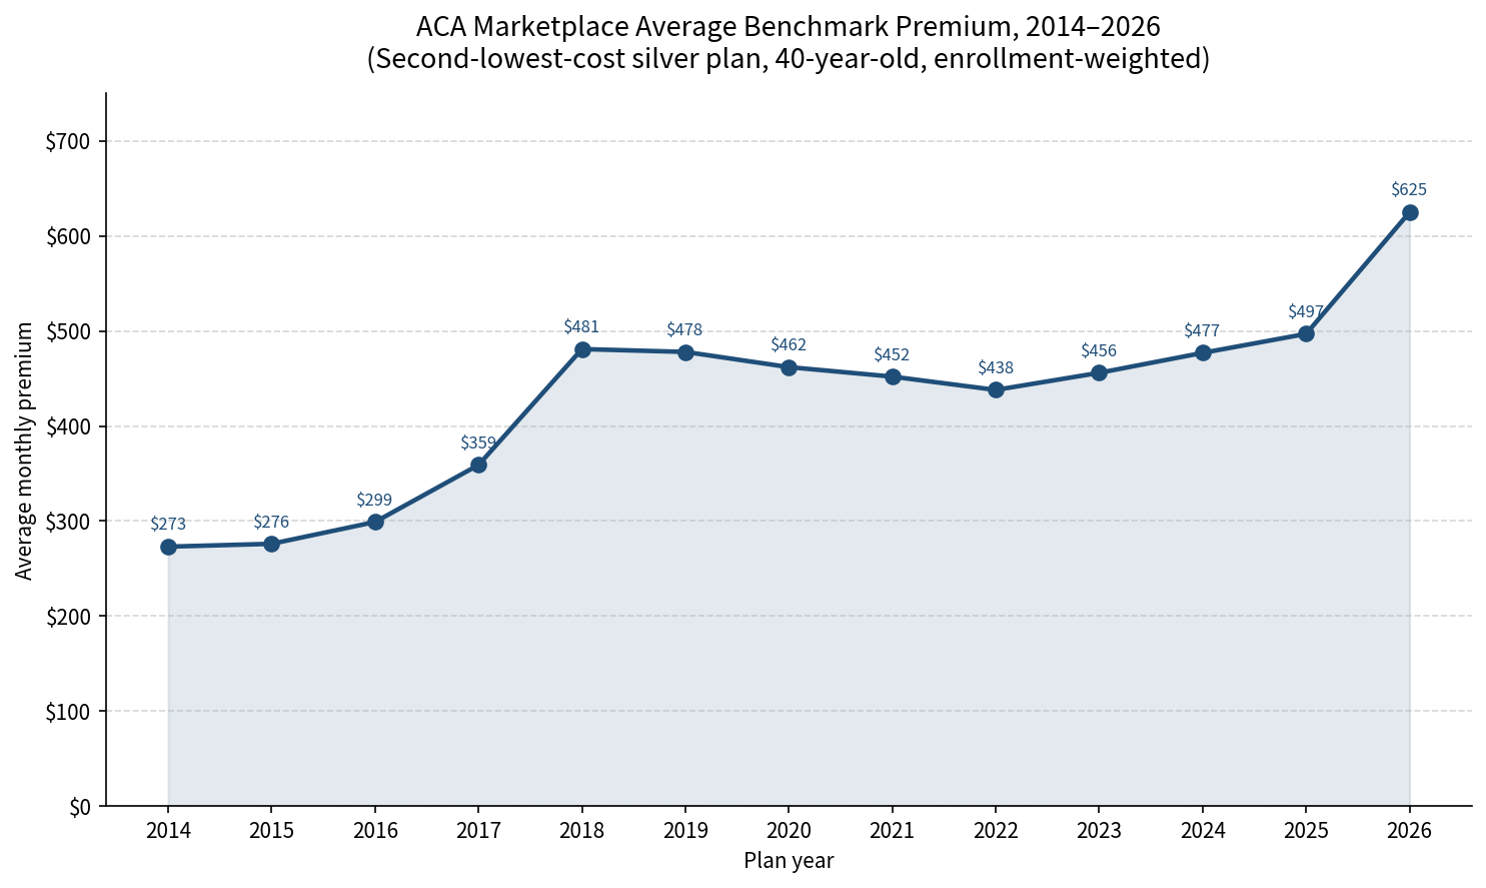
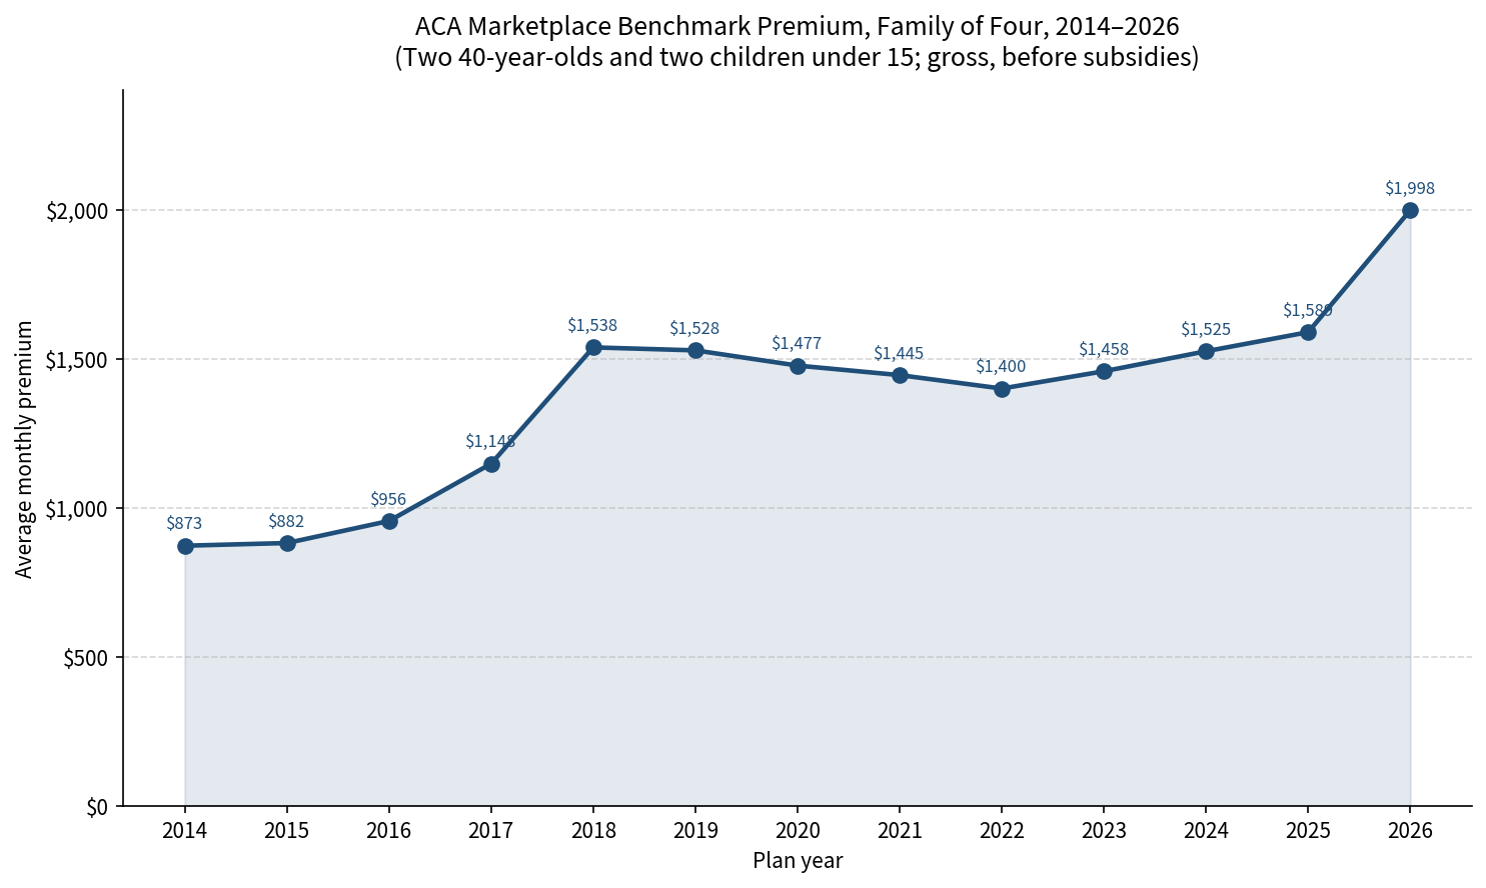
The political problem is that prices on the exchanges are soaring, pretty much having doubled since 2014. Even the lowest and most minimal package of supposed benefits is going to cost nearly as much as a mortgage. For this reason, many people are simply doing without. Already this year, an estimated 3 million have dropped medical insurance entirely.
Contrary to what you hear, prices are out of control. The system is unsustainable as is.
Herein lies the problem. These checks are arriving now but there is no way to use them for health insurance other than going back to the exchanges themselves. And there people face the same problems they always have.
The exchanges have pre-defined benefits packages. You might not want wellness checkups and mental health care but you have to buy it anyway. There is no minimalist option at all. You cannot just buy coverage for extremely rare emergency events. If that were available, it is obviously true that most people would buy it. This is precisely why it is not available: most people would switch, hence gutting the entire system of revenue.
In addition, the premiums you pay are not actually adjustable by one’s own health risk. This means that calling this insurance is really a misnomer. Your car insurance premiums adjust based on your driving record. Your home insurance adjusts based on the risk of fire or flood. Your life insurance changes dramatically depending on your risk of dying, and you can be sure that a complete physical exam is necessary before the policy is signed.
None of this is true with this fake medical insurance. There is a community rating that pools risk among a wider group. You could decide to lose weight, eat right, join a gym, and otherwise shape up your life, and it will make zero difference in the premium you pay. Why bother?
In fact, since this program went into place 15 years ago, Americans have lost every bit of financial reward that might otherwise be associated with getting and staying healthy. What do you think would happen? It is more-then-obvious exactly what would happen. If you are paying the same either way, you might as well live it up, take risks, and let your health collapse. That is exactly what has happened since the advent of Obamacare.
So these aspects of the program need to be completely changed. If nothing else, insurers should be allowed to offer minimalist coverage for those who are healthy and don’t want to pre-pay for a bunch of services that they neither want nor need.
Herein lies the core problem. Trump’s intuition is correct that the money should be given back to the individuals and families. But right now, without dramatic reform, they have no choice but to put the new funds back into the exchanges that are the problem in the first place.
This is a bit like giving tax refunds but providing no option but to use them for the payment of taxes. The purpose is thereby defeated. The Republicans had plenty of opportunity over these nearly two years to reform the system fundamentally. They have not made it a priority at all. They have completely neglected the entire issue even as the system as it is is in an advanced state of falling apart.
We are far too long down this path of wreckage for a $500 check to make much difference. If that money could go into an HSA and be tax-free provided it was spent on medical issues and otherwise invested in financial markets, we would be in a position to begin the process of having the system reform itself. We need more options. The system needs decartelization.
It makes no sense for an advanced nation to sit by and watch its entire medical sector implode piece by piece and do nothing. We urgently need universal HSAs, opt-outs for employees and employers, premiums that adjust by real risk, and a mix of benefits that the consumer chooses rather than one that government chooses for us. All of this is obvious.
There are less obvious reforms. We have already growing numbers of crowd-health solutions. This is not insurance. It is a way of gaining coverage, leverage in negotiations, and sharing the cost of unexpected expenses with others. These systems work extremely well. If employees could be allowed to use them while dropping their employer-provided plans in exchange for salary, millions would jump in. This is a minor change but a massively impactful one.
Trump’s $500 checks idea comes from a good place but it is only a tiny start. The system as it is cannot adapt to what he envisions, which is a world in which patients and their providers are in charge. We need much else on the reform table to make this vision a reality.
Views expressed in this article are the opinions of the author and do not necessarily reflect the views of The Epoch Times.
 Friends Read Free
Copy
Facebook
Tweet