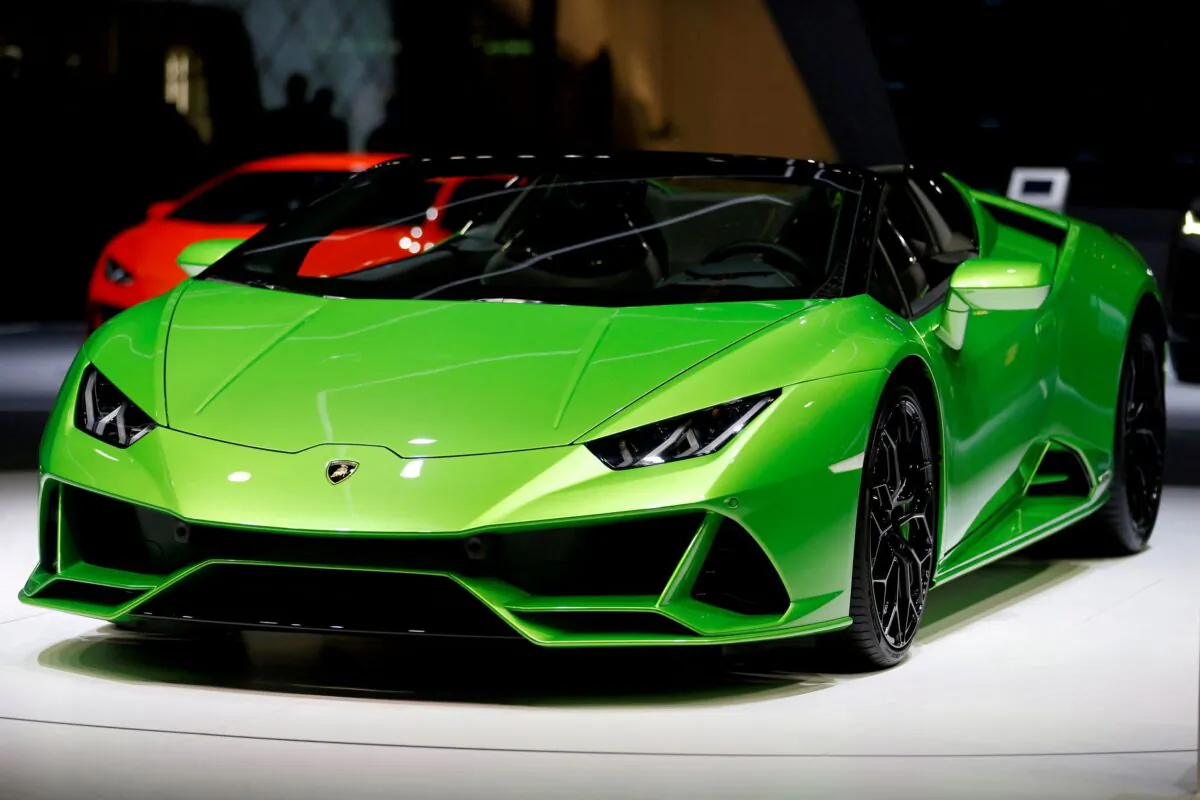
New car financing hit a new high in the third quarter, with buyers borrowing record amounts to fund vehicle purchases, according to auto review platform Edmunds.
The average amount financed for a new vehicle was a record $44,664 in the third quarter, up from $42,744 in the third quarter of last year, Edmunds said in an Oct. 1 statement.
In addition, a record 25.5 percent of new vehicle financing was in loans with a term of 84 months or more. This is up from 21.8 percent a year ago.
Monthly payments on new vehicles are also setting records. In the third quarter, the average monthly payment on new vehicles was $787, a new high. New car buyers are agreeing to $1,000-plus monthly payments at higher rates, according to Edmunds.
Combined, these trends have pushed auto borrowing costs to all-time highs.
Jessica Caldwell, an assistant vice president at Edmunds Insights, said in the statement that the data show robust consumer resilience.
“Even as monthly payments hit record highs, loan terms stretch to historic lengths, and four-figure monthly payments become more common, buyer demand for new vehicles hasn’t dropped off,” Caldwell said.
“Instead of sitting on the sidelines, consumers are adapting: They’re allocating more of their household budgets to their vehicles, stretching out their loan terms, and becoming more proactive about shopping around for financing to find ways to make the numbers work.”
Despite high borrowing costs, new-vehicle sales continue to remain strong. According to a recent report by industry expert Cox Automotive, annualized total vehicle sales, which measures what total annual sales would be if a single month’s pace continued all year, increased to 16.80 million units in August from the previous month.
Sales this year are trending up, driven mostly by interest from affluent households. Cox said it expected September sales to be 6.5 percent higher year over year and to remain strong for the remainder of 2026.
In a Sept. 30 statement, Edmunds highlighted a shift in market trends in vehicle model sales. Ivan Drury, Edmunds’ director of insights, said that the end of summer typically leads to sell-down events, when sellers look to offload the outgoing model year.
However, automakers were not in the usual rush to move on from the 2026 models this September, Drury said.
“The 2026 models are still selling at a healthy pace. Shoppers holding out for massive year-end blowout sales shouldn’t assume they’re a given,” Drury said.
“There may not be a magic moment to buy this year, so consumers need to be as diligent as ever and be ready to act when the right deal comes along rather than waiting for the calendar to deliver one.”
The Trump administration has taken certain steps to address high car prices and loan costs.
In January, Treasury Secretary Scott Bessent announced that the department was implementing a tax deduction for car loan interest, in line with the provisions of the One Big Beautiful Bill Act.
In a post on X, Bessent said eligible taxpayers could deduct up to $10,000 per year in auto loan interest on new U.S.-assembled vehicles purchased in 2025–28.
More recently, on Sept. 28, the National Highway Traffic Safety Administration finalized new fuel economy standards for cars and light trucks.
Specifically, the agency lowered Biden-era mileage targets for these vehicles. According to the agency, the new update is expected to cut the average car price by $1,300 and save Americans around $138 billion over the coming five years.
The Alliance for Automotive Innovation, which represents most major automakers, welcomed the new update in a Sept. 28 statement.
“The standards finalized under the previous administration effectively required a switchover to electric vehicles that was out of step with market realities and customer demand,” John Bozzella, president and CEO of the alliance, said in the statement.
“Today’s final rule is an appropriate course correction.”
 Friends Read Free
Copy
Facebook
Tweet