Americans’ incomes and net worth rose in the years after the pandemic, the Federal Reserve said in a new report covering 2022–2025.
Despite inflation climbing to its highest level in 40 years after the public health crisis, U.S. households survived economic storm clouds, with many families thriving.
Real (inflation-adjusted) median family income rose 7 percent in the three-year span to $82,200. Low-income families saw the largest gains, with the bottom 60 percent increasing by up to 7 percent. By comparison, the top 10 percent posted a 6 percent decline in real income.
This mirrors the post-crisis labor market, which tilted in workers’ favor. Employers, mainly in the services sector, bolstered wages and offered bonuses to attract talent.
Real median net worth rose 2 percent to nearly $216,000. Most families across the income and wealth groups registered increases, according to the central bank’s data.
“In contrast to income, changes in wealth largely reinforced existing patterns of wealth inequality by family characteristics,” the central bank wrote. “Families that typically have less wealth (such as young families, renters, and families without a high school diploma) saw median and, oftentimes, mean wealth declines.”
By contrast, families positioned near the top—high-income households, older families, and asset owners—enjoyed some of the largest wealth gains.
The Fed’s triennial Survey of Consumer Finances, released on Oct. 9, surveys more than 4,000 households and provides a snapshot of U.S. families’ financial conditions.
Its recent findings align with the Census Bureau’s glowing report about U.S. households.
Last month, the federal agency reported that household incomes climbed to an all-time high in 2025. Poverty, meanwhile, fell to a record low.
Asset Ownership
Asset ownership—stocks and real estate, for example—has contributed to America’s growing net worth.
The homeownership rate held steady at 66 percent, and homeowners’ median net housing value jumped to $230,000 last year, from below $219,000 in 2022.
Existing home prices have accelerated over the last few years as pandemic-era ultra-low interest rates created a golden handcuffs effect. This has forced millions of homeowners to stay put and refrain from listing their property for sale.
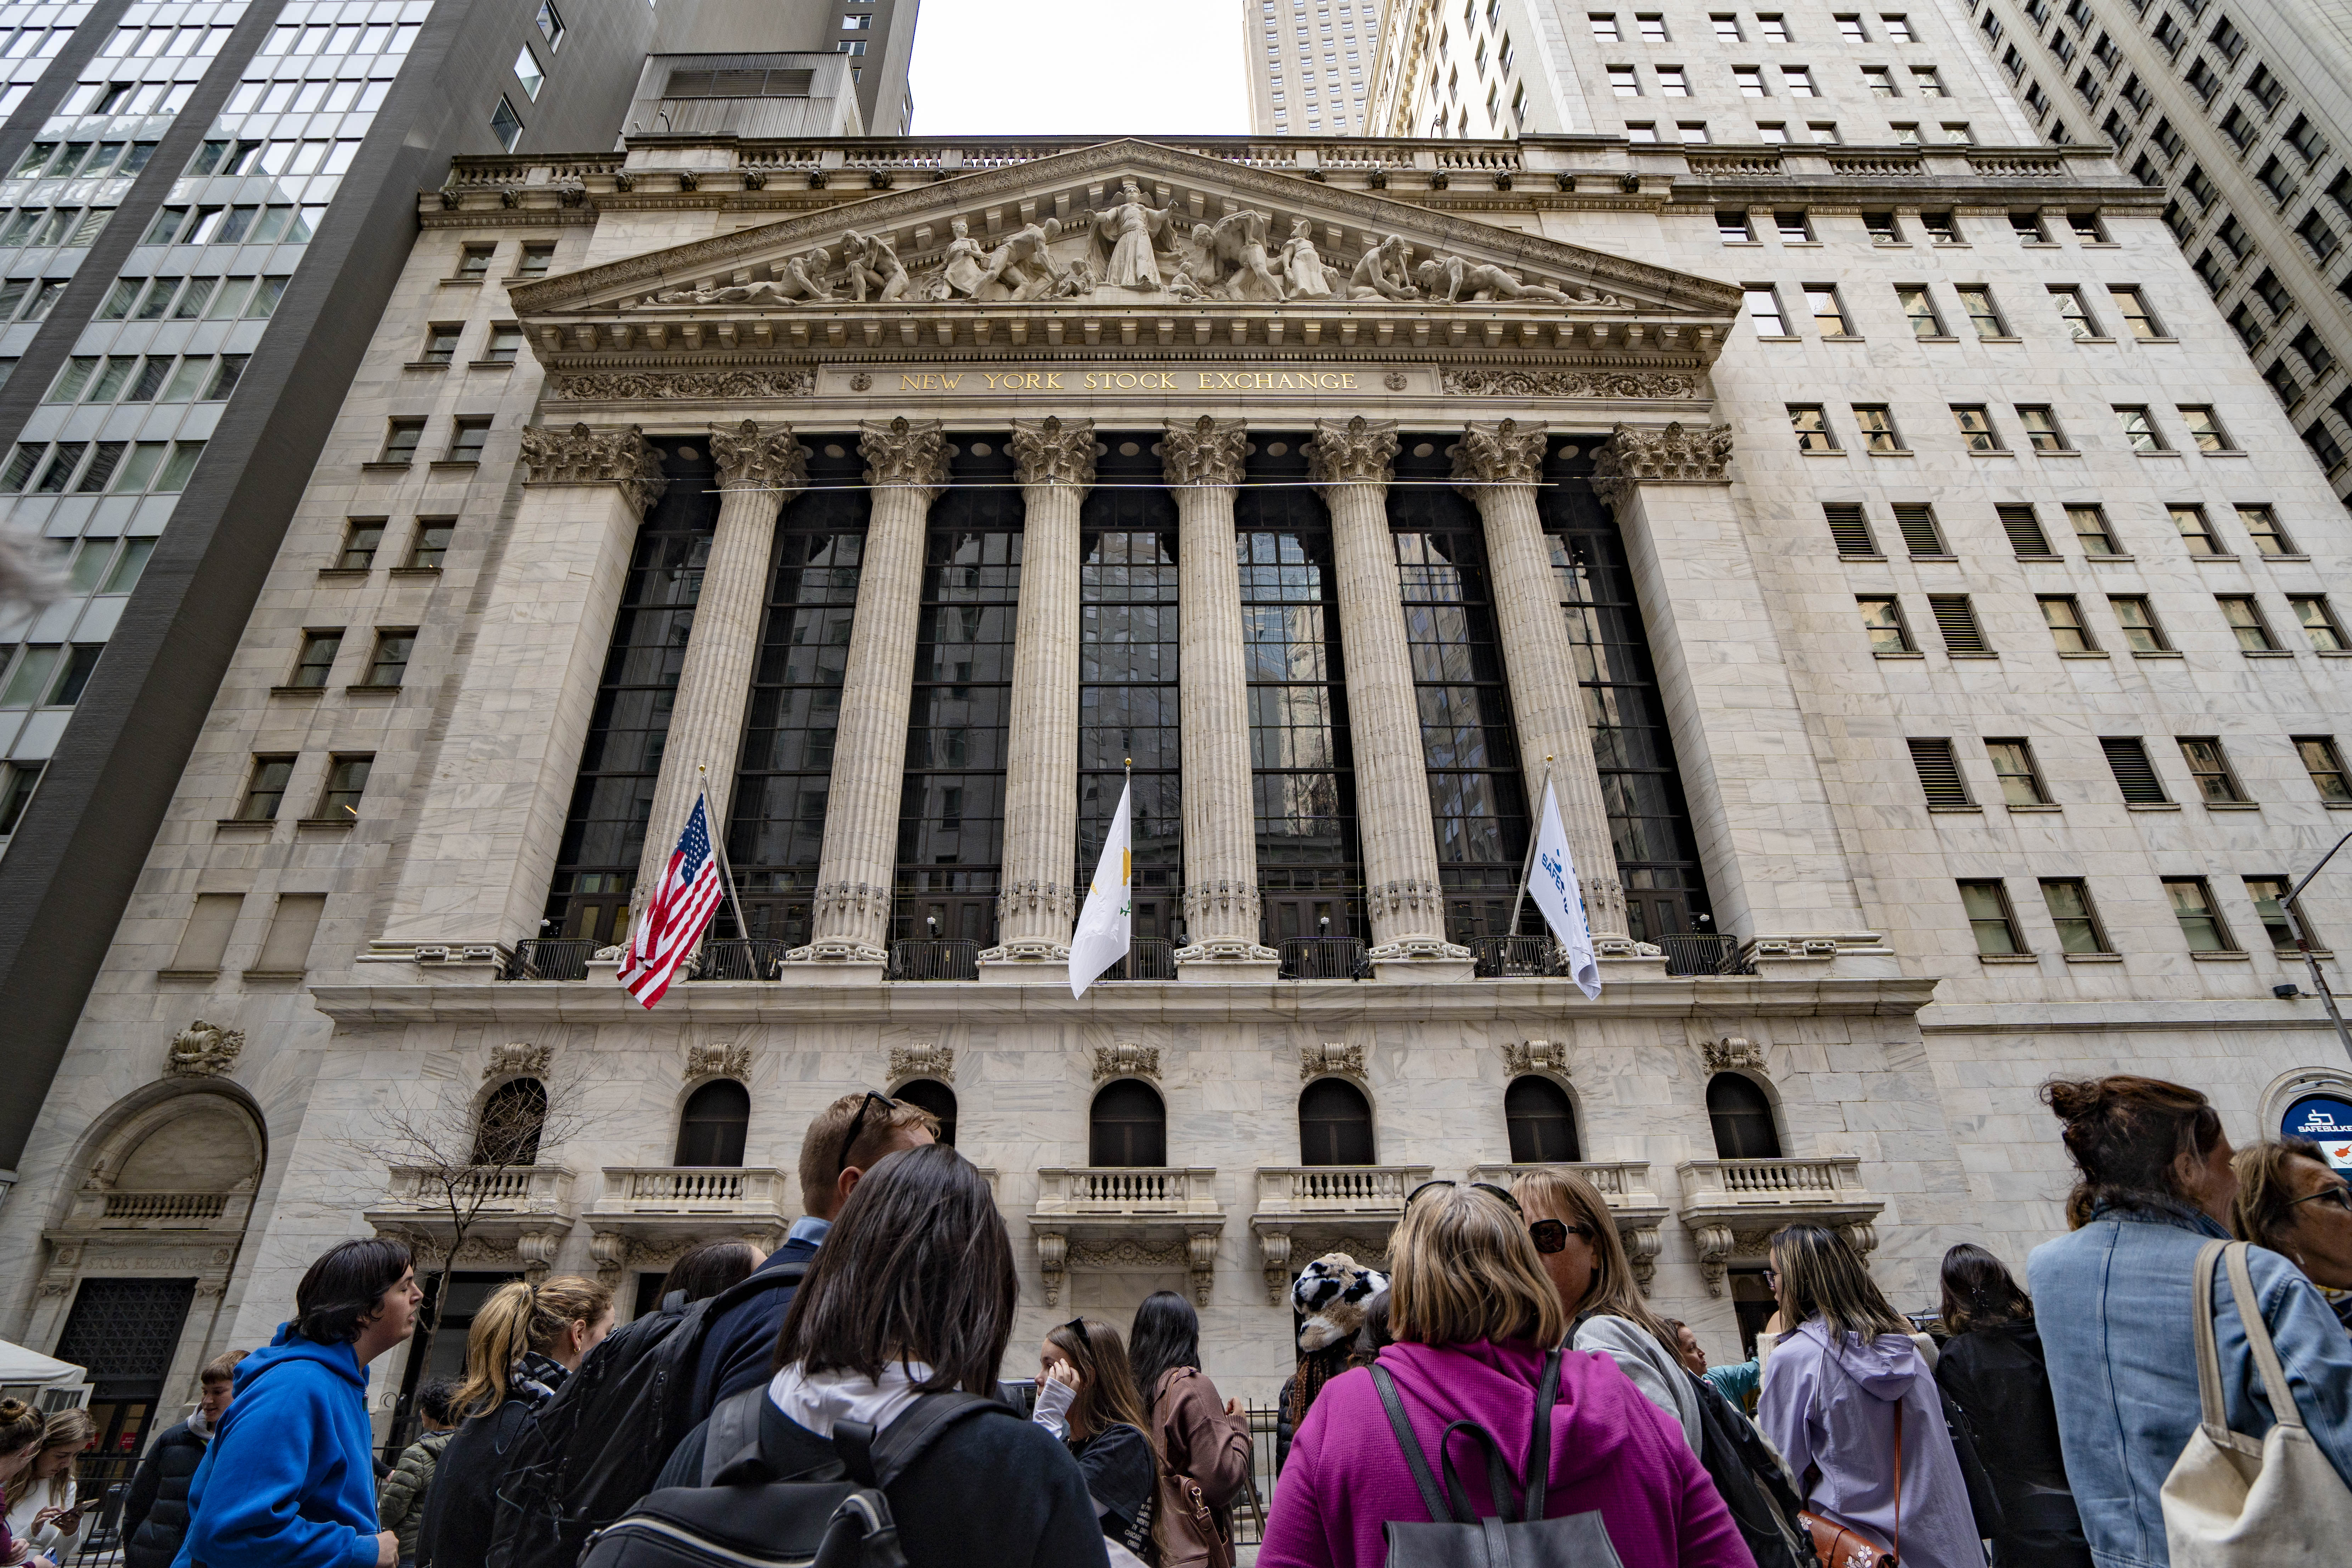 The New York Stock Exchange in New York City on April 4, 2025. (Samira Bouaou/The Epoch Times)
U.S. stocks are still surging, with institutional and retail traders sending the tech-heavy Nasdaq Composite Index and the broad-market index S&P 500 to record levels.
Red Ink
Household debt remained prevalent after the pandemic. The share of families carrying any debt was little changed at 77 percent, and median balances were unchanged. The share of families with credit card debt stayed flat at 45 percent, and the median balance rose at a tepid pace, from $150 to $3,100.
At the same time, debt stress levels could be building.
Debt-payment-to-income ratios above 40 percent rose from 6.5 percent to nearly 9 percent, the highest level in more than a decade. The share of families reporting they fell behind on loan payments swelled to 20 percent, up from 12 percent in 2022.
“Borrowers look less financially fragile when their debts are scaled to their assets rather than to their income,” the Fed report authors said.
“Families’ propensity to stay current on their financial obligations worsened between 2022 and 2025. Families were more likely to be behind on their financial obligations than at any point since the 2010 survey.”
Servicing these debts could be borrowers’ next challenge as interest rates creep up.
One credit component that may also require further monitoring is buy-now, pay-later loans—also known as BNPL.
“The growing popularity of BNPL, which is typically used for smaller purchases, explains nearly all the growth in the percentage of families with other installment loans in 2025,” the report stated.
Twelve percent of families posted a balance on a BNPL plan, up from 7 percent in 2022.
A June paper by Fed economists estimated that BNPL providers originated approximately $160 billion in consumer credit products.
 Friends Read Free
Copy
Facebook
Tweet