Commentary
The U.S. equity market is once again at or near all-time highs.
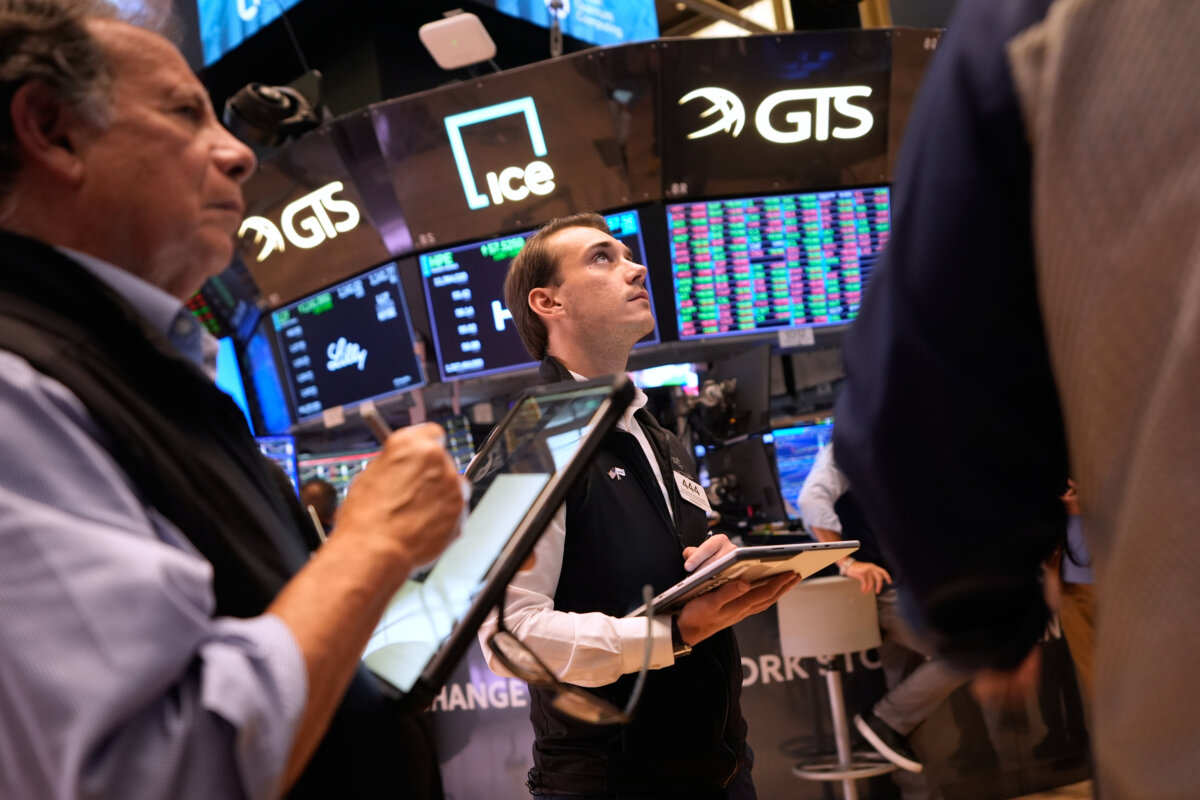
On Monday, Oct. 5, the technology-heavy Nasdaq Composite closed at a record 27,477.31, gaining approximately 1.1 percent. The S&P 500 rose 0.66 percent to 7,773.95, just below its previous record, while the Dow Jones Industrial Average also moved higher. Nvidia reached a record market capitalization of approximately $5.76 trillion.
As I wrap up this article on Tuesday morning, Oct. 6, at approximately 11:00 a.m. ET, the Dow Jones, Nasdaq Composite, and S&P 500 remain firmly higher, with the S&P 500 having already reached a new intraday record.
The artificial intelligence (AI) trade remains powerful. Corporate earnings expectations are strong. Investors continue to buy technology and large-cap growth stocks. Yet beneath the surface, several technical and fundamental signals deserve closer attention. The question is not whether the market can continue rising. It clearly can.
The more interesting question is: What could cause the current market structure to change—and how quickly could that happen?
Market Breadth: What Is Happening Beneath the Index?
One of the most important issues in a market approaching record highs is breadth—how many stocks are actually participating in the advance. Major U.S. equity indices are market-cap weighted. When the largest companies rise sharply, they can push the entire index higher even if a significant number of individual stocks are lagging.
That makes index-level strength somewhat misleading. A market can, therefore, appear exceptionally healthy even as leadership becomes increasingly concentrated among a relatively small group of companies.
Recent trading illustrates this dynamic. On Oct. 5, the Nasdaq reached another record close, yet the underlying breadth was considerably less impressive: the index recorded 57 new 52-week highs versus 243 new lows. Within the S&P 500, there were 13 new highs versus 20 new lows.
These numbers do not automatically signal that a correction is imminent. Narrow leadership can persist for a long time, particularly when the companies driving the market have genuine earnings power, strong balance sheets, and secular growth opportunities.
But when major indices continue making records while fewer stocks participate, the market can become increasingly sensitive to a negative catalyst.
The indicators I would monitor include:
-
The percentage of stocks trading above their 50-day moving averages
-
The percentage trading above their 200-day moving averages
-
Advance-decline lines
-
New 52-week highs versus new lows
-
Equal-weighted versus capitalization-weighted indices
-
Small-cap performance relative to large-cap technology
Breadth deterioration does not tell us when a correction will occur. What it does tell us is that the market may become increasingly sensitive to a negative catalyst.
Earnings Season: Can Fundamentals Catch Up With Expectations?
The third-quarter earnings season is now underway, with companies beginning to report their Q3 2026 results. Expectations are unusually strong. FactSet, a leading provider of financial data and analytics used by institutional investors, estimates that S&P 500 earnings will grow approximately 29.5 percent year over year in Q3 2026.
More importantly, analysts have raised their earnings estimates during the quarter rather than cutting them. FactSet also projects approximately 27.6 percent earnings growth for Q4 2026.
That is an important distinction. A market trading at elevated valuations can continue to perform well if earnings growth continues to validate those valuations. The problem arises when expectations become too high.
The current investment narrative is heavily influenced by AI, data-center spending, semiconductor demand, and the expectation that enormous capital expenditures will eventually translate into equally enormous earnings and cash flows. The market, therefore, needs to see more than revenue growth.
The Magnificent Seven: The Next Major Test
The next major test will come from the Magnificent Seven: Nvidia, Microsoft, Apple, Alphabet, Amazon, Meta and Tesla. Their combined market capitalization has become so large that their earnings results can influence not only individual share prices, but also the direction of the major U.S. equity indexes.
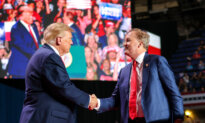
 U.S. President Donald Trump, sitting next to Nvidia CEO Jensen Huang (L) and SpaceX CEO Elon Musk (R), speaks during a meeting with technology executives about artificial intelligence, in the East Room of the White House in Washington on Sept. 29, 2026. (Kent Nishimura/AFP via Getty Images)
For investors, these reports are more than individual corporate events. They represent a test of the AI earnings narrative itself.
The key questions will be whether cloud and AI revenue continue to accelerate, whether margins remain resilient, how aggressively capital expenditure is increasing, and whether management teams can demonstrate an attractive return on the enormous investment being made in AI infrastructure.
Given the concentration of index performance in these companies, a series of disappointments or cautious forward-guidance revisions could have an impact far beyond the individual stocks. That is why the coming earnings cycle may be one of the most important fundamental tests for the current rally.
Rates, Valuation, and the Mechanics of a Drawdown
Another issue is the relationship between equity valuations and interest rates. The striking feature of the current market is that equities are making record highs while Treasury yields remain elevated.
On Oct. 5, the 10-year Treasury yield reached approximately 5.31 percent, its highest level since April 2002. For long-duration growth stocks, higher yields can pressure valuations by raising the discount rate applied to future cash flows. Earnings can remain strong while valuation multiples contract.
Tariffs and trade policy are another potential catalyst. The April 2, 2025 tariff announcement demonstrated how quickly a policy shock can move through financial markets. Over the following two trading sessions, April 3 and 4, the S&P 500 fell approximately 11 percent as investors reassessed the potential impact on corporate profits and economic activity.
This is particularly relevant to technology and semiconductor companies with globally integrated supply chains.
The key risk is when several factors reinforce each other: higher yields → valuation compression → technology weakness → deteriorating breadth → increased volatility → further selling.
The initial catalyst may be relatively modest. The feedback loop is what can turn a normal correction into a much larger drawdown.
October and the Midterm Election: What Does History Actually Tell Us?
October has an extraordinary reputation in financial markets. The crashes of 1929, 1987, and 2008 all contribute to the perception that October is uniquely dangerous. But history is more nuanced.
October is not automatically a crash month. The same principle applies to the U.S. midterm election. The Nov. 3 election will undoubtedly create political uncertainty, but history does not support using the midterm election itself as a standalone bearish signal.
Markets ultimately respond to the interaction between politics and fundamentals. If an election changes expectations regarding taxation, regulation, fiscal policy, or trade, sectors that are highly sensitive to those variables may react.
But if corporate earnings remain strong and financial conditions remain supportive, the market can absorb substantial political uncertainty. Therefore, I would not attempt to forecast a market correction simply because October has arrived or because the midterm election is approaching.
Instead, I would view the election as a potential amplifier of volatility if the market is already experiencing deterioration in breadth, earnings expectations, or financial conditions. That distinction is important. Political uncertainty can increase volatility. It does not necessarily determine market direction.
The Bottom Line: Earnings Are Strong, But Expectations Are Even Higher
A market at an all-time high, by itself, is not sufficient evidence of an impending correction or bear market. In fact, strong markets can remain overbought, concentrated, and expensive for much longer than investors expect.
A more rigorous assessment requires examining breadth, concentration, valuation, earnings expectations, interest rates, liquidity and positioning. At present, the fundamental backdrop remains strong.
S&P 500 earnings are expected to grow approximately 29.5 percent year over year in Q3 2026, and analysts have been raising rather than cutting their estimates. FactSet also currently expects approximately 27.6 percent earnings growth for Q4 2026. That is an important counterargument to the bearish case.
The market can continue higher if earnings validate current expectations. But the market is also operating with elevated Treasury yields and significant dependence on a relatively small group of mega-cap technology and AI companies.
That creates an interesting asymmetry. If the Magnificent Seven continue to deliver accelerating earnings, resilient margins and strong returns on AI investment, the current market structure can remain intact.
But if earnings expectations deteriorate, rates rise further, breadth weakens, and positioning begins to unwind, the downside could become disproportionately large relative to the initial catalyst. The same concentration that has helped drive the Nasdaq to record levels could therefore amplify a reversal if the fundamental narrative changes.
Therefore, the key question is not whether the market is at an all-time high.
It is: Are the earnings, breadth, and liquidity conditions sufficiently robust to sustain the valuation structure supporting that all-time high?
That is the question I would be asking as we move through October, the Magnificent Seven earnings cycle, and into the final weeks before the 2026 midterm election.
At an all-time high, the market does not necessarily need a major economic shock to correct. Sometimes, all it takes is for expectations to change.
Views expressed in this article are the opinions of the author and do not necessarily reflect the views of The Epoch Times.
 Friends Read Free
Copy
Facebook
Tweet