Veteran mortgage broker Ron Butler says that as the Bank of Canada is expected to raise interest rates, some realtors may urge prospective home buyers to act quickly to avoid potentially higher borrowing costs. But Butler advises buyers not to rush, saying there could be further changes in the market.
Butler, who has worked in the industry for over three decades, said rapidly climbing fixed mortgage rates may lead to a small upsurge in activity among buyers who had previously secured rate holds or mortgage pre-approvals. But he said prospective buyers should be wary of real estate agents who suggest they have only a brief window to buy before rates rise further.
“There’s a brief flurry of those people running out and saying, ‘I’ve got this low rate. I want to capitalize on it. I got this rate hold, so I’ve got to buy a house quickly and make use of my rate hold,’” Butler told The Epoch Times. “But that’s only a small, small subset of people.”
He added that he expects most prospective buyers to wait and see whether rates come down, saying rapidly changing rates tend to pause buying activity rather than produce a sustained rush into the market.
Five-year fixed-rate mortgage offerings ranged from 4.34 percent to 4.69 percent as of Sept. 29, according to Ratehub.
Butler says buyers with an existing lower rate-hold might rush to use it before it expires, while most other prospective buyers would likely pull back.
“Rapid rate change stops everybody. It pauses everybody who might be thinking about buying a house,” Butler said.
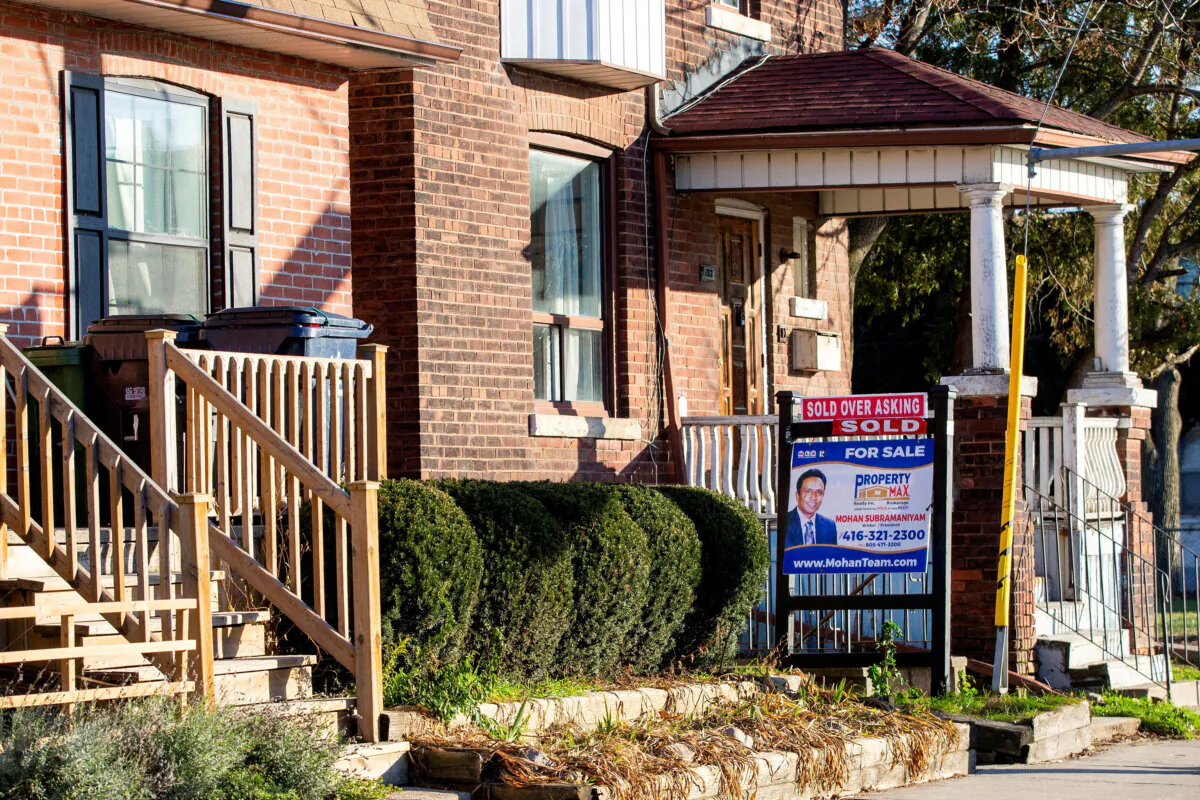
Butler’s advice comes as higher mortgage rates add pressure to Canada’s housing market, contributing to weaker sales.
Home sales across the country fell 0.7 percent between July and August of this year and were down 6.9 percent in August 2026 compared to August 2025, according to a Sept. 15 release from the Canadian Real Estate Association (CREA).
CREA senior economist Shaun Cathcart has also warned that higher fixed mortgage rates, driven in part by rising government bond yields, along with broader economic challenges in Canada, are likely to further slow the housing market heading into 2027.
“For borrowers, fixed mortgage rates have already increased on higher bond yields. Meanwhile, on the variable rate side, a rate hike is not only back on the table for this year but already priced in by markets,” Cathcart wrote in a Sept. 15 update. “This fresh round of incoming headwinds is expected to dampen the prospects for further housing market momentum heading into 2027.”
In terms of housing prices, an outlook published by the CREA this July forecasts an average national home price hike of 1.1 percent in 2026 and again in 2027, with slight declines in average home prices expected in Ontario and B.C. this year.
Beware Pressure Tactics
With higher rates and weaker sales creating ongoing uncertainty in the housing market, Butler said prospective buyers should be especially wary of “buy now” pressure tactics from those who suggest prices will never come down again.
Butler advised prospective buyers to consider to similar arguments made when home prices rapidly went up in 2021, before the housing market began turning and prices fell in many areas in 2022 and beyond.
“Back in 2021, all realtors said that, ‘hey, just put in as high a bid as you can on a house now because the prices will go up forever and you’ll never own a home,’” Butler said. “It is an evil tactic,” he added.
Nonetheless, Butler said he doesn’t expect a rush of home purchases to occur, and said there is likely to be only a “tiny, almost insignificant burst of selling and buying, and then it’s gone.”
“You have to have a rate hold in writing, and that’s a small, small subset of people. But it does create this little tiny blip for the next few weeks, and then it goes away,” he added.
 Friends Read Free
Copy
Facebook
Tweet