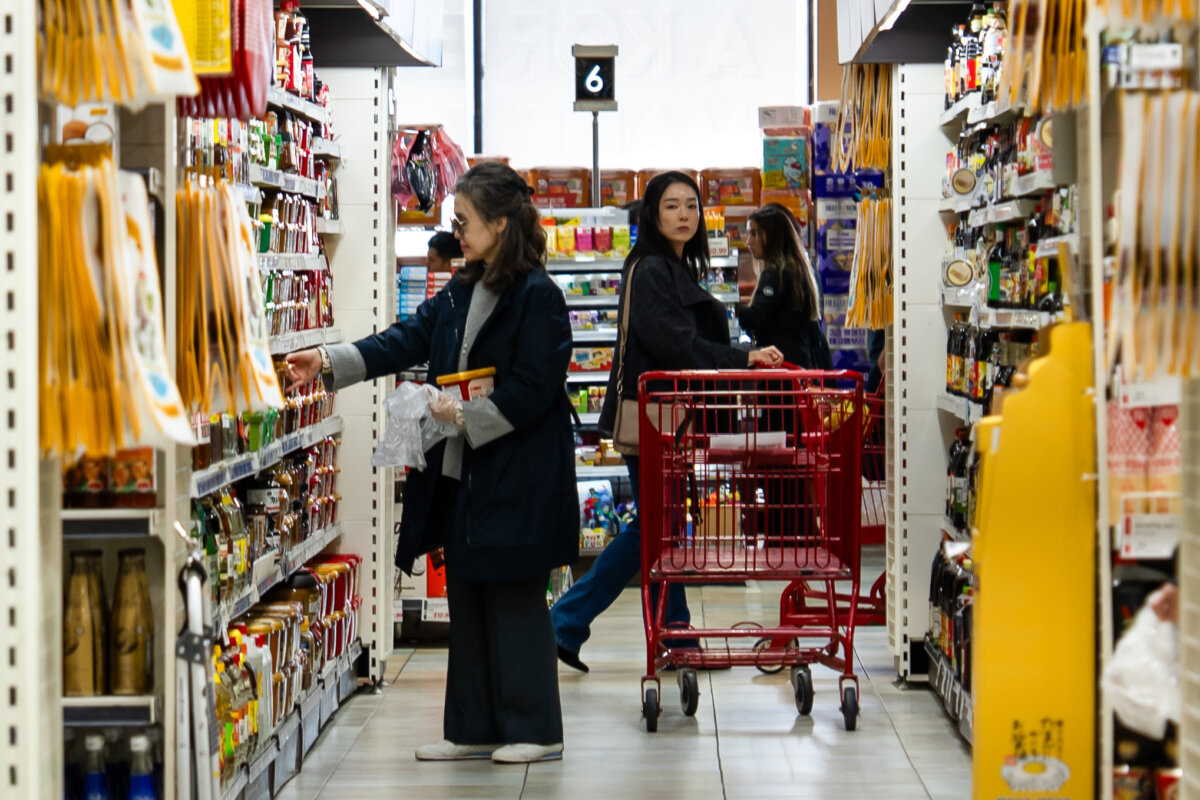
Consumers remain downbeat about the U.S. economy as affordability challenges persist.
The University of Michigan’s October Consumer Sentiment Index declined almost 4 percent to 46.3, from September’s 48.1. This is also down nearly 14 percent from a year ago.
October’s reading represented the second-lowest on record.
Economists’ consensus estimate pointed to 47.6.
Views of current economic conditions fell sharply by more than 12 percent to 44.7, reflecting tougher buying conditions for durable goods.
The year-ahead outlook for the economy improved by about 2 percent to 47.3.
“Frustration over cost-of-living continues to mount, as consumers across the political spectrum believe that the trajectory of the economy has weakened since the beginning of the year,” Joanne Hsu, director of consumer surveys at the university, said in a statement.
Consumers’ inflation expectations ticked up slightly this month, with the one-year forecast rising to 4.7 percent from 4.6 percent in September. Long-run inflation expectations edged up to 3.5 percent, from 3.4 percent.
Various consumer surveys this year have echoed similar gloomy sentiment.
The Conference Board’s September Consumer Confidence Index fell to its lowest level in 12 years, underscoring sharply weaker views of business conditions and the labor market.
Likewise, the New York Fed’s Survey of Consumer Expectations showed that the one-year inflation forecast rose by 0.3 percentage points to 3.9 percent.
As before, consumers’ frustrations with the economy largely stem from inflation.
Headline inflation—the annual rate sits well above 3 percent—has eroded workers’ earnings. In August, real (inflation-adjusted) average hourly wages have dipped 0.3 percent year-over-year, the Bureau of Labor Statistics said last month.
Renewed inflation pressures are primarily fueled by surging global energy prices. Gasoline, for example, is now at record highs for autumn, according to the American Automobile Association. As of Oct. 9, the national average is above $4.37 per gallon.
“This is the first year the national average has been above $4 per gallon in October,” the group said in an Oct. 8 blog post.
At the same time, consumers are contending with rising interest rates.
The U.S. Treasury bond market is in turmoil, with the benchmark 10-year yield at its highest level in more than 20 years, trading around 5.25 percent.
With the Federal Reserve expected to raise interest rates to combat inflation, financial conditions could tighten, meaning it becomes more expensive for consumers to borrow.
A Possible Drag on Demand
The university found worsening sentiment among “groups that have fewer resources to weather increases in prices.”
Sentiment fell sharply for low-income consumers and individuals who maintain smaller stock portfolios.
Economists warn that the United States may be drifting toward a K-shaped economy, where higher-income households continue to pull ahead while lower-income groups fall further behind.
While consumers have been resilient in today’s economic climate, ongoing sentiment deterioration could eventually filter through to the broader market and weigh on demand, says Antonio Di Giacomo, senior market analyst at XS.com.
“The deterioration in sentiment matters because it could lead to greater caution in spending, particularly on nonessential goods and services,” Di Giacomo said in a note emailed to The Epoch Times. “If households reduce their spending, companies could struggle to sustain sales growth,” he continued.
Sentiment does not necessarily confirm a decline in consumption, but it can signal that it would adversely affect upcoming data, including retail sales, he added.
So far, despite worsening sentiment, consumers continue to open their wallets.
Retail sales rebounded 1.2 percent in August. Consumer spending is also projected to be the top contributor to third-quarter economic growth, according to the Atlanta Federal Reserve. The regional central bank expects an expansion of almost 4 percent.
The upcoming earnings season could also offer insight into consumer behavior as major U.S. banks report on credit demand, loan portfolios, and financial activity, Di Giacomo noted.
 Friends Read Free
Copy
Facebook
Tweet